Myth vs. Reality—Does the Fed Control Mortgage Rates in Metro Portland & SW Washington?
Myth vs. Reality—Does the Fed Control Mortgage Rates in Metro Portland & SW Washington?
 Key Takeaway: As of late 2026, one of the most persistent misconceptions among local buyers and sellers across the Portland-Vancouver Metropolitan Area (spanning Clark County in Washington, and Multnomah, Washington, and Clackamas Counties in Oregon) is that the Federal Reserve directly sets mortgage rates. The reality is that the Fed sets the overnight Federal Funds Rate, while 30-year fixed mortgage rates track the 10-Year Treasury Yield, which moves dynamically based on broader inflation expectations, labor reports, and geopolitical headwinds. With regional active inventory stabilizing near 3.8 to 3.9 months of supply and local median home prices holding at $540,000 to $555,000 in Metro Portland and $525,000 to $573,000 in Clark County, waiting for Fed rate cuts before making a move can cost buyers significant time and equity. Local buyers and sellers are instead taking control of today's market by structuring seller-paid 2-1 mortgage rate buydowns, locking in pre-approvals, and pricing to match current purchasing power.
A Note of Comfort for Your Move (Entity Connection)
 If you've been refreshing financial news feeds and feeling anxious every time a Federal Reserve meeting makes headlines, take a deep breath and pause. Feeling protective of your hard-earned savings while trying to make sense of conflicting interest rate projections is a sign of smart, practical household leadership. Please take comfort in knowing that the Fed does not hold a dial that controls your homebuying or selling success in Oregon and Southwest Washington. You do not have to put your family's housing plans on ice waiting for policy shifts. As experienced local real estate advisors and dedicated advocates, Ken and Susan Rosengren with Lucido Global at Keller Williams Premier Partners are here to cut through national media noise with factual, neighborhood-level numbers. Call Ken directly at 360.609.0226 or Susan at 360.607.6678. We wrap a protective, data-backed strategy around your goals so you can make your next move with total confidence and peace of mind.
🗺️ Myth vs. Reality: The Mechanics of Mortgage Rates 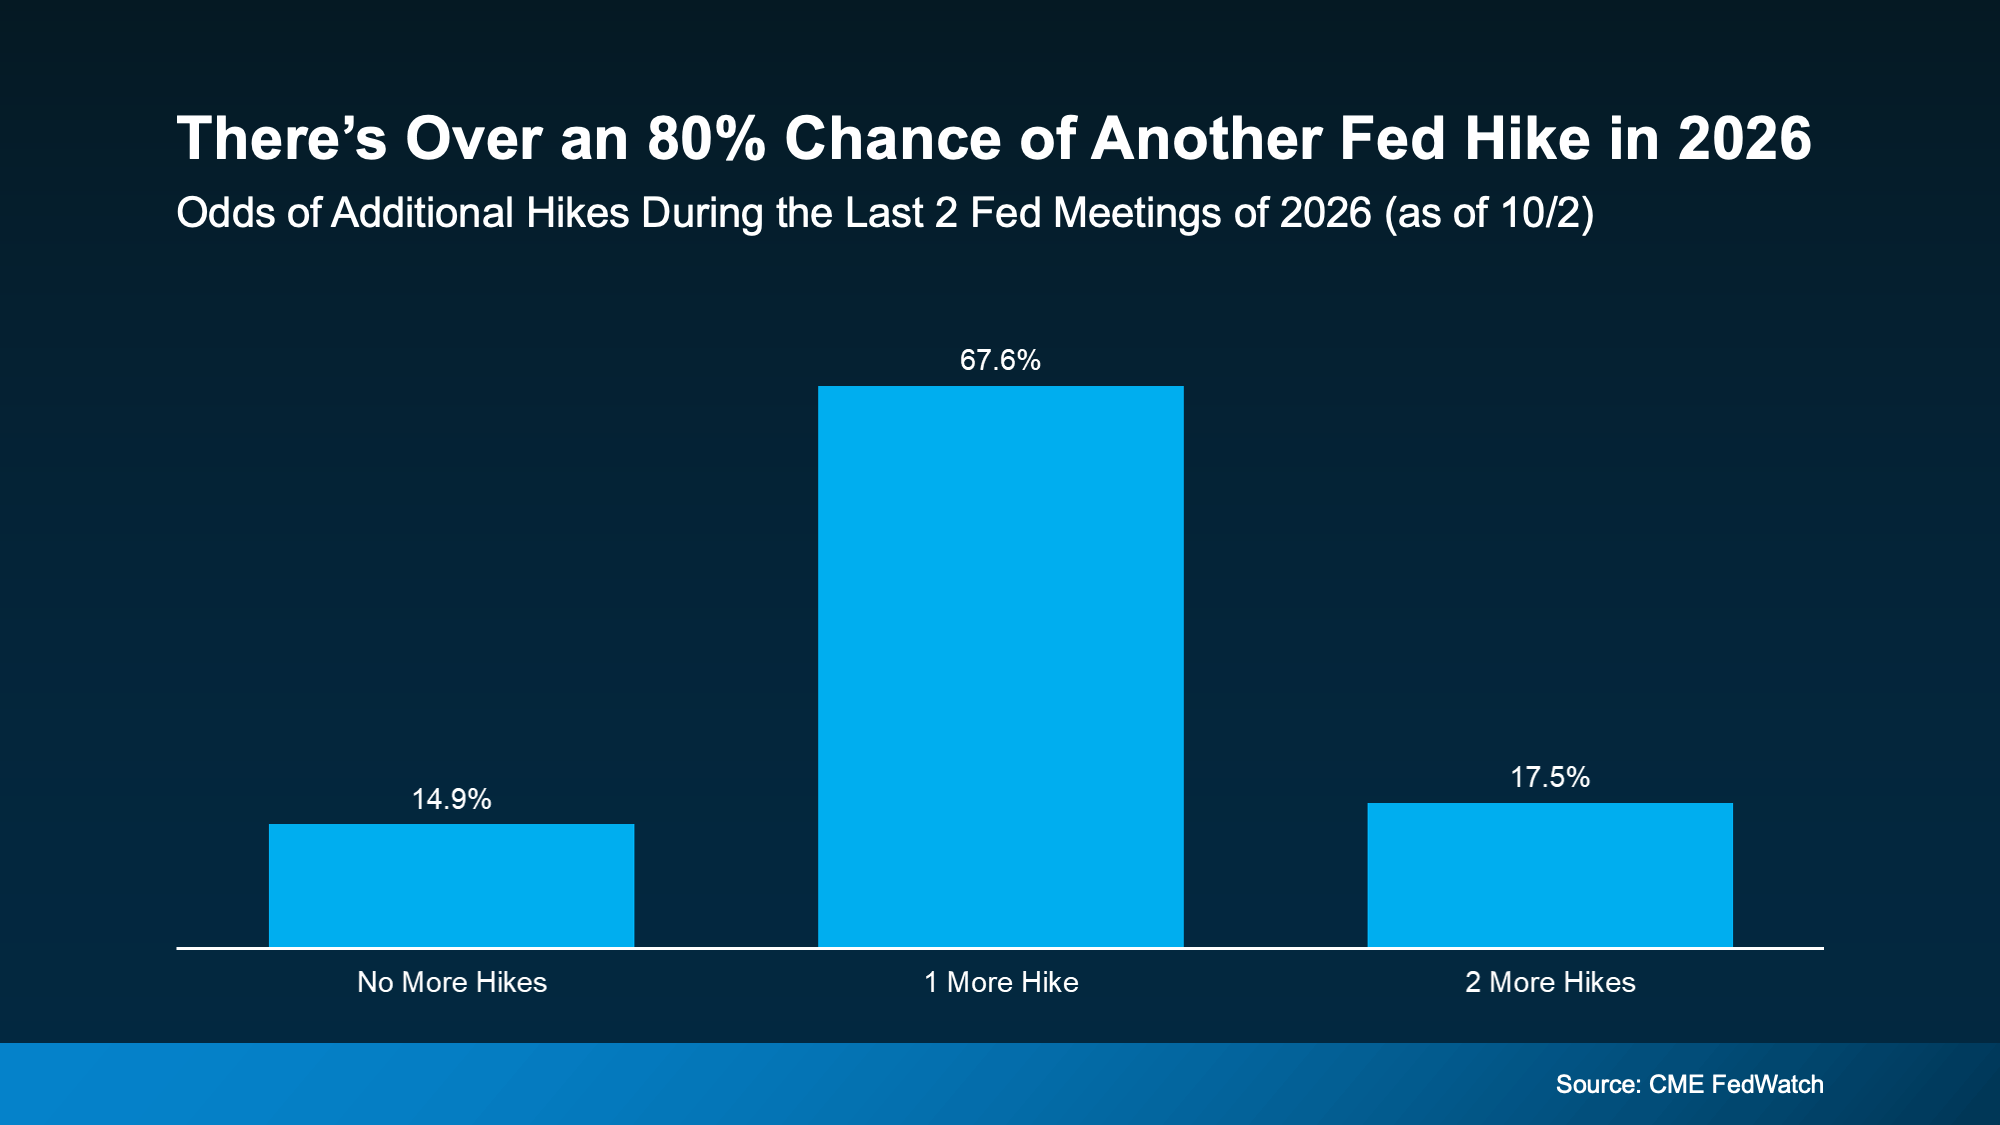
Understanding the relationship between monetary policy, bond yields, and daily home loan pricing provides clarity for local decisions:
-
The Myth: When the Federal Reserve raises or lowers interest rates, mortgage rates immediately move by the exact same percentage points.
-
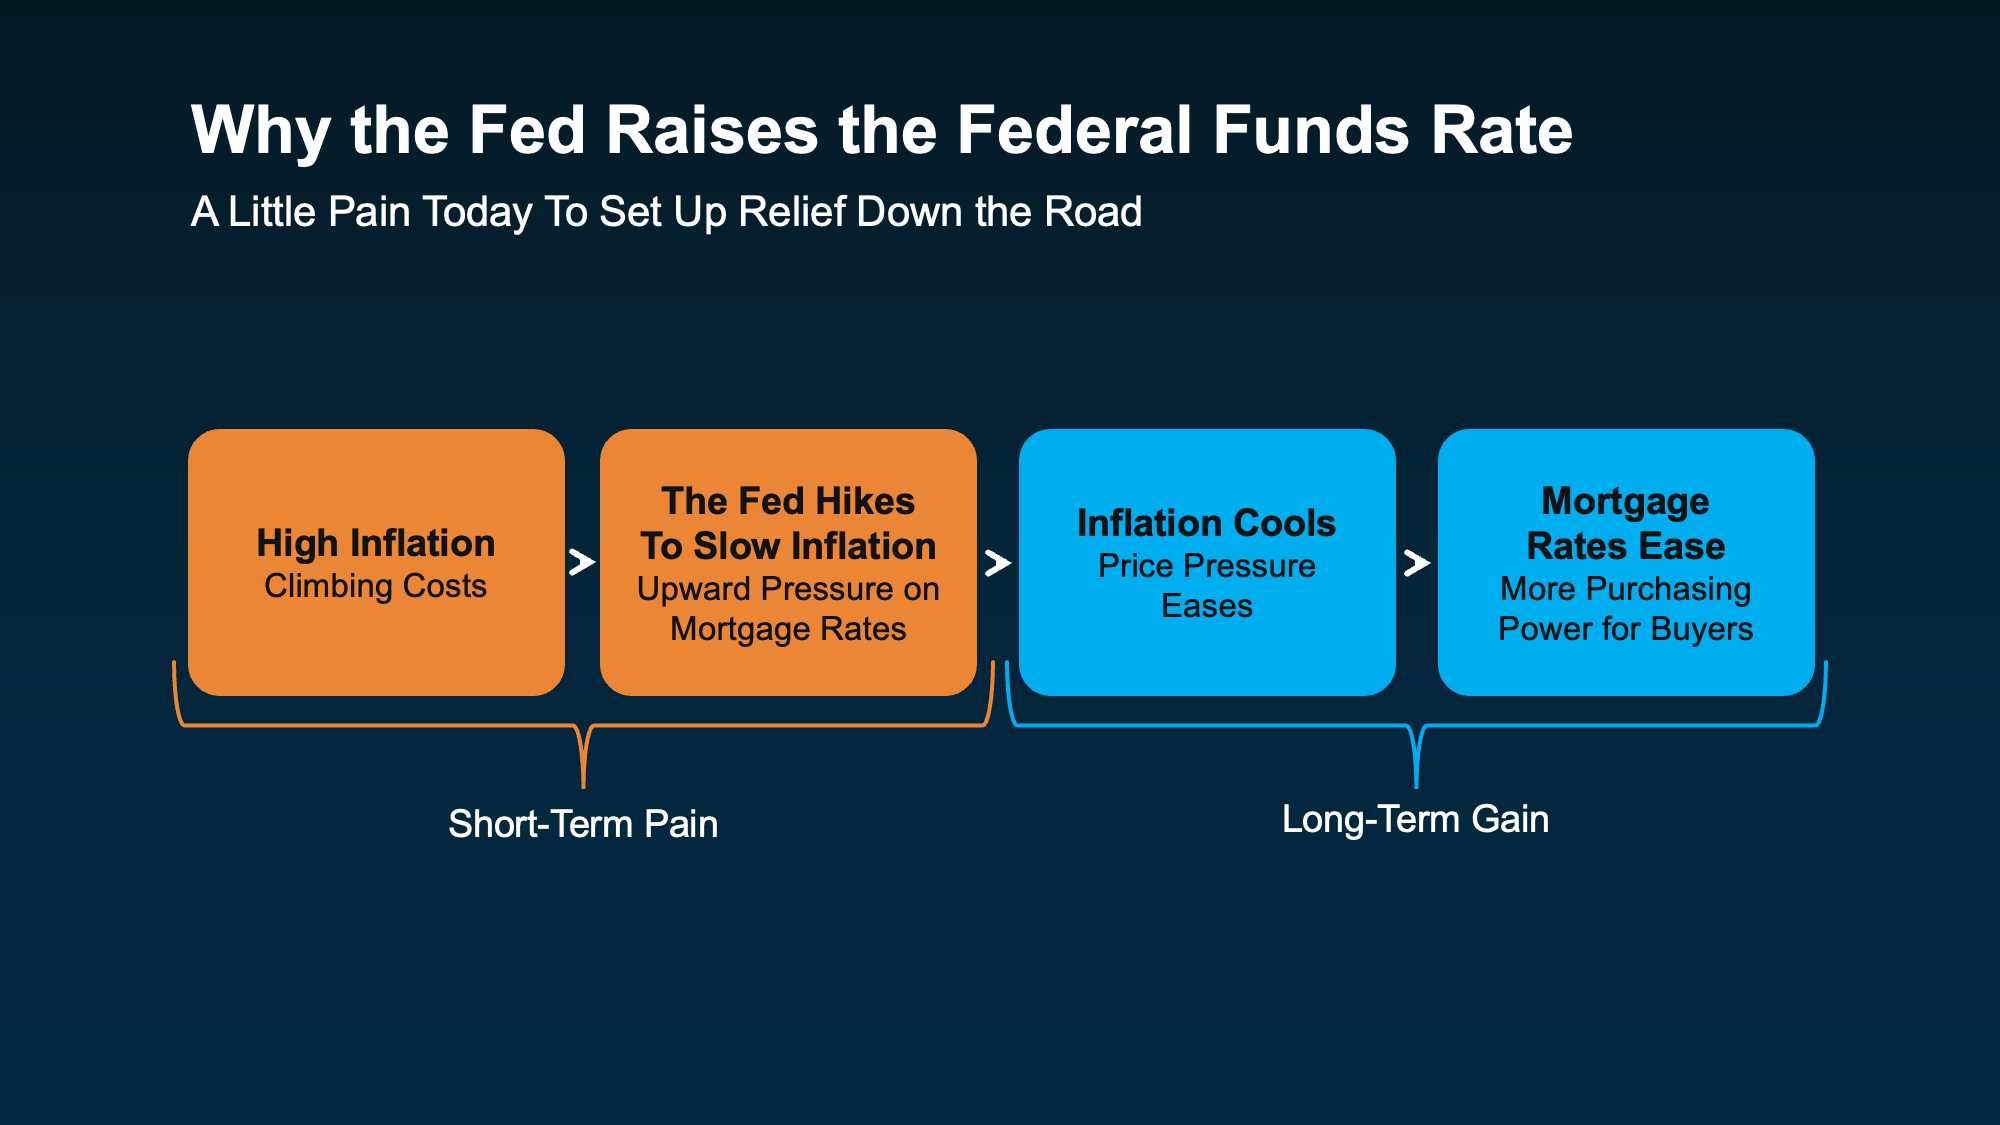
The Reality: The Fed directly controls the short-term Federal Funds Rate (the rate commercial banks charge one another for overnight loans). Long-term 30-year fixed mortgage rates, however, are traded on secondary bond markets as Mortgage-Backed Securities (MBS) and correlate closely with the 10-Year Treasury Yield.
-
The Inflation Driver: Long-term bond investors demand higher returns when inflation is elevated to preserve their purchasing power over a 10- to 30-year horizon. When headline inflation cools (such as recent Core PCE drops toward 3.0%), bond yields relax—often allowing mortgage rates to drift downward even before the Fed officially cuts its benchmark rate.
📊 Regional Market & Financing Snapshot: Metro Portland OR vs. Clark County WA (Late 2026 Data)
To evaluate how interest rate movements and local inventory levels intersect across our bi-state metro area, review current RMLS and regional baseline numbers:
| Submarket Hub | Median Closed Home Price | Months' Supply of Inventory | Average Days on Market | Strategic Rate & Negotiation Opportunities |
| Portland Metro Area (OR) | $540,000 - $555,000 | 3.8 Months | 54 - 57 Days | Elevated inventory gives buyers strong leverage to secure $10k–$15k seller credits for rate buydowns. |
| Clark County / Vancouver (WA) | $525,000 - $573,000 | 3.9 Months | 26 - 36 Days | Average sale-to-list ratio near 97.5%; zero state income tax in WA preserves buyer monthly cash flow. |
| Suburban Growth Corridors (Ridgefield, Battle Ground, Hillsboro) | $485,000 - $525,000 | 4.1 Months | 60 - 65 Days | Builders and resale sellers competing actively; high prevalence of 2-1 rate buydowns and closing cost help. |
💡 Practical Playbook: Making Your Move Work at Today's Rates
Rather than trying to time unpredictable macroeconomic cycles, buyers and sellers in Oregon and Southwest Washington can execute targeted tactics to achieve their financial goals:
For Local Buyers:
-
Secure a Verified Pre-Approval & Rate Lock: Move beyond general pre-qualification. Work with a trusted local lender to verify income and credit documentation. Once under contract on a home in Vancouver or Portland, use an upfront rate lock to protect against mid-escrow market volatility.
-
Negotiate a Seller-Funded 2-1 Mortgage Rate Buydown: Instead of using negotiation leverage solely to ask for a list price discount, request a $10,000 to $15,000 seller credit at closing to fund a 2-1 temporary rate buydown. This drops your effective mortgage rate by 2.0% in year one (e.g., from 6.75% down to 4.75%) and 1.0% in year two, delivering immediate monthly savings when you need them most.
-
Explore New Construction & Low-Down Programs: Expanding communities in Ridgefield, Camas, and South Hillsboro feature builder-funded rate incentives well below secondary market averages. First-time buyers can also explore low-down-payment options (3% to 3.5% down) and state programs like WSHFC or OHCS to preserve liquid savings.
For Local Sellers:
-
Price to Current Buyer Purchasing Power: Buyers in today's mid-6% interest rate climate calculate monthly payments down to the dollar. Pricing your listing accurately from day one based on recent 30-day hyper-local comparable sales prevents your home from sitting past its prime initial marketing window.
-
Offer Rate Concessions Upfront: Advertising a seller-paid concession toward a buyer's rate buydown or closing costs often costs you less than an arbitrary $20,000 price drop, while creating far greater payment relief for your prospective buyer.
-
Explore Interactive Valuation and FSBO Landing Pages: Before launching your listing, take advantage of our custom digital resources to review your bottom-line numbers:
-
Calculate Your Current Home Equity: Request your personalized report via our Free Home Valuation Landing Page.
-
Considering an Independent Sale? Access checklists, worksheets, and resources via our Free FSBO Success Program Landing Page.
-
🛠️ The Bottom Line: Formulate a Strategy for Today's Market
The Federal Reserve influences economic conditions, but it does not control the mortgage rate you can secure or the terms you can negotiate on a home in Oregon or Southwest Washington. Waiting for perfect market timing often leads to missed opportunities while home prices continue their steady historical climb.
Whether you are shopping for your first home in Vancouver, upgrading in Beaverton, or preparing to sell in Camas or Lake Oswego, having trusted local advisors in your corner makes all the difference.
Reach out today, and let’s construct a clear, personalized roadmap that works smoothly in today's market!
Connect with Our Team Today
No high-pressure sales pitch. No automated scripts. Just honest local numbers, deep community insights, and a protective strategy built entirely around your family's financial goals.
Ken Rosengren
📞 Phone: 360.609.0226
📧 Email: KenRosengren@LucidoGlobal.com
Susan Rosengren
📞 Phone: 360.607.6678
📧 Email: SusanRosengren@LucidoGlobal.com
Lucido Global at Keller Williams Premier Partners
2211 E Mill Plain Blvd, Vancouver, WA 98661
Helping families build long-term wealth through education, planning, and homeownership.
#PortlandRealEstate #VancouverWARealEstate #ClarkCountyWA #LucidoGlobal #MortgageRates2026 #FederalReserve #RateBuydown #PNWRealEstate #RealEstateExpert #MarketLeaderPNW #PremierAgent
Categories
- All Blogs (659)
- For Sale By Owner (21)
- Local Events (39)
- Portland Metro (2)
- 100 Hands for Foster Care (2)
- 1031 Exchange PNW (1)
- Affordability (69)
- Agent Value (105)
- Battle Ground (2)
- Boutique Neighborhoods (1)
- Brush Prairie WA (1)
- Buying Tips (236)
- Camas High Schools (1)
- Camas WA (1)
- Camas WA Home Buying (1)
- Camas WA Real Estate (2)
- Central Hub (1)
- Clark County Housing (25)
- Clark County WA Schools (3)
- Closing Costs (1)
- Community Support (17)
- Cowlitz County (1)
- Credit Tips (2)
- Debt-Free Living, (1)
- Design (8)
- Downsize (13)
- Downsizing Vancouver WA (13)
- Economy (28)
- Equity (37)
- Evergreen High Schools (1)
- Expired Listings (1)
- Featured (20)
- Felida WA Home Buying (1)
- Felida WA Real Estate (1)
- Financial Planning (43)
- First-Time Home Buyer (196)
- For Investors (1)
- For Sale by Owner (6)
- Forecasts (17)
- Foreclosures (6)
- Foster Care Resrources (2)
- Fun Tips (10)
- Giving Back (1)
- Historic Charm (1)
- Historical Character (1)
- Hockinson WA (1)
- Home Buying (299)
- Home Improvement (1)
- Home Inspections (3)
- Home Prep & Staging (5)
- Home Prices (77)
- Home Selling (206)
- Home Staging PNW (1)
- Home Value (10)
- Housing Market Confidence (47)
- Independent Living PNW (2)
- Inventory (41)
- Kalama WA (1)
- La Center (1)
- Landlord Tips (2)
- Lifestyle Move PNW (24)
- Listing Strategy (5)
- Local (106)
- Local Non-Profits (1)
- Longview WA (1)
- Luxury / Vacation (7)
- Market Update (66)
- Mid-Tier Housing (1)
- Mortgage (71)
- Move-Up (16)
- Moving for Job Relocation (5)
- Multi-Generational (1)
- Negotiation Strategy (4)
- New Construction (15)
- Newsletter (14)
- Open House (1)
- Portland Downsizing (10)
- Portland For Sale by Owner (1)
- Portland OR (9)
- Portland OR Affordability (41)
- Portland OR Home Buying (88)
- Portland OR Homes (9)
- Portland OR Real Estate (123)
- Portland OR Seller Tips (40)
- Portland Real Estate FAQs (10)
- Portland Recession Risk (1)
- Portland-Vancouver Home Value (13)
- Portland-Vancouver Inventory (10)
- Price It Right Portland (8)
- Real Estate Investing (8)
- Real Estate Tax Strategy (1)
- Rent vs Buy (19)
- Restaurant Reviews (5)
- Retirement Planning (2)
- Ridgefield WA (1)
- Ridgefield WA Home Buying (1)
- Rightsizing Vancouver WA (3)
- Seasonal (11)
- Selling Rental Property (2)
- selling tips (141)
- Senior Market (6)
- Silver Group (3)
- Suburban Living (3)
- Technology (1)
- Teens & Young Adults (11)
- Trends (15)
- Vancouver For Sale by Owner (2)
- Vancouver WA (9)
- Vancouver WA Affordability (36)
- Vancouver WA Home Buying (75)
- Vancouver WA Home Value (7)
- Vancouver WA Real Estate (125)
- Vancouver WA Selling Tips (40)
- Washougal WA (1)
- Wealth Building (20)
- Yacolt WA (1)
Recent Posts